Mexico Offers Excellent Value in Latin America

The S&P 500 is down 3.7% YTD as of market close Monday. Closely tracking the U.S. market is Mexico’s IPC All-Share Index which is down 4.2%.

Due to the strong ties between U.S. and Mexico, the Mexican economy moves up and down in tandem with the U.S. economy.However due to weaker fundamentals Mexican investments suffer greatly when the U.S. underperforms.

The economy of Mexico is finally improving after the worst recession in almost a century. Mexico’s international reserves reached a record $95. 7 billion in March. The oil and manufacturing sectors are showing strong improvements and Mexican exports increased by 39% in March relative to March 2009. The automotive industry, one of the most important industries in the country, is recovering strongly with production and exports up in the first four months of this year.The unemployment rate in the first quarter stood at 5.3%. (Source: CEIC Macro Watch).

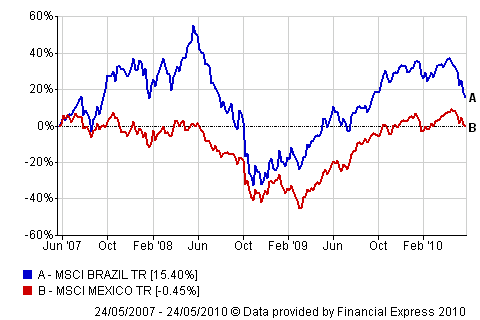
Accordingly The MSCI Mexico Index has recovered strongly and has currently reached the pre-credit level. However when compared to Brazil, Mexico took a longer time to reach this level from the October 2008 lows as the chart shows below:

Country Performance: Mexico vs. Brazil
Mexico-Brazil-Performance-3-Years

Source:  Financial Express Analytics

Due to the contrast in the pace of rebound between Mexico and Brazil, many value plays can be found in Mexican equities. Some of the Mexican stocks to consider are telecom providers Telemex(TMX) and America Movil(AMX),  airport operators Grupo Aeroportuario del Centro Norte (OMAB), Grupo Aeroportuario del Pacifico (PAC) and Grupo Aeroportuario del Sureste (ASR), cement maker Cemex(CX) and beverage company Coca Cola Femsa(KOF). TMX offers a 5.87% dividend yield now.The three airport operators hold long-term concessions and will benefit as the number of tourists visiting the country increases. In addition to Mexico, Coca-Cola Femsa (KOF) derives a significant portion of revenue from distribution of its products in other Latin American countries.

Another simple to invest in Mexican equities is to invest via the iShares MSCI Mexico Investable Market Index ETF (EWW).
Will Chinese Savers Stampede Into Stocks Now?

The Shanghai Composite index is down over 21% as of last Friday and continues to fall further. An article titled “Chinese Savers Turn to Their Stockbrokers” in the latest edition of Bloomberg BusinessWeek suggests that equities are now preferred over savings and real estate.

From the article:

“Ordinary Chinese investors are looking to stocks for a lift. If they’re not careful, they may get the opposite.

Although the Shanghai Stock Exchange Composite Index is down more than 21 percent this year, Pan Weiting sees no better place to put her money. The 27-year-old Shanghai accountant recently shelved plans to buy an apartment after real estate prices reached record highs. The 2.25 percent interest she earns on the 400,000 yuan ($59,000) she has in her bank account is being nibbled away by rising inflation, which hit 2.8 percent in April.

If Pan were an American, she might switch to international stocks, gold, or municipal bonds. China’s financial regulations, however, limit her investment choices to property or domestic equities. It’s no contest. “The stock market is the best choice for the moment,” says Pan. “Even the bank staff advised me against depositing more money.”

Millions of other Chinese, who on average save half their income, share Pan’s dilemma. Property prices are often out of their reach. If they do buy real estate, they risk seeing their investment wiped out should the government’s recent curbs on mortgage loans finally chill the market. Inflation is forecast to climb 3.4 percent this year, according to the median estimate of 18 economists surveyed by Bloomberg on May 11. That will put more pressure on low-yielding savings accounts. “It becomes a question of who’s the least ugly girl at the fair,” says Victoria Mio, a Hong Kong-based senior fund manager at Robeco, whose firm manages $194 billion worldwide. “There is migration [to stocks] occurring, and the shift will accelerate with a few months of negative interest rates.”” (emphasis added)

Chinese households have very low debt levels.The household debt as a percentage of GDP is about 10% .In general, Chinese households save over 25% of their disposable income.Savings by businesses and households push the gross domestic savings as a percentage of GDP to exceed 50%.The combined personal and corporate savings in China equals $7.2 Trillion.

Some of the reasons mentioned in the article for anticipated the flow of funds into equities include:

  • Low to negative interest rates on bank savings accounts
  • Rising inflation rate. Inflation is projected to climb 3.4% this year
  • Falling real estate prices as authorities have increased bank reserve requirements to slow lending

Despite all the reasons mentioned above, I believe Chinese savers are not going to rush into equities. Many global issues such as the European debt crisis, the chances of the global economy going into a double-dip recession, the Korean issue, etc. may affect the Chinese economy leading to accelerated decline in share prices. In addition, culturally the majority of the Chinese are very conservative and prefer property investments and savings to stocks.

The 10 Most Profitable Indian Companies

The 10 most profitable publicly-listed Indian companies that appear in the Forbes Global 2000 list for 2010 are listed below:

[TABLE=504]

Except IT outsourcing firm Infosys Technologies (INFY), none of the other companies trade on the US markets. The most profitable company in India is the state-owned Oil & Natural Gas Corp. which made$3.86B last year. State Bank of India, India’s largest bank is also state-owned and was ranked at number three. It must be noted that Indian banks such as State Bank of India and ICICI Bank(IBN) have a long way to go before they can become global players. For example, though banks in India operate in different dynamics than their western counterparts, profits earned by Indian banks are low compared to international banks. For example, State Bank of India’s profit of $2.13B for the full year pales in comparison to Bank of America’s profit of $4.2B just in the first quarter of 2009.

ETFs to invest in India:

iShares S&P India Index Fund (INDY)
PowerShares India Portfolio (PIN)
WisdomTree India Earnings Fund (EPI)

The Largest 13 U.S. Banks by Market Capitalization

The four largest “Too Big To Fail(TBTF)” U.S. banks Bank of America (BAC), JPMorgan Chase(JPM), Citigroup (C) and Wells Fargo(WFC) continue to remain as the largest banks in the country. These TBTF banks are also known as the superbanks.

From a November, 2009 article titled Too-Big-To-Fail and the Theory of Large Numbers  by Henry C.K. Liu:

“JP Morgan Chase is reportedly holding more than $1 of every $10 on deposit in the US. The four biggest super banks (JP Morgan Chase, Bank of America, Wells Fargo and Citibank) now issue one of every two mortgages and about two of every three credit cards in the US. Since the financial crisis, these four super banks are each allowed to hold more than 10% of the nation’s deposits, having been exempted from a longstanding rule barring such market dominance. In several metropolitan regions, these new super banks are now permitted to take market share beyond what the Department of Justice’s antitrust guidelines previously allowed.  Such concentration of market share will hurt consumers in two ways. It will keep cost of credit high to borrowers for lack of competition even when cost of fund for banks remains artificially low. It will also push bank reserves upward to force banks to pass on the cost to borrowers. The American banking system is now one of a handful of large global trading companies pretending to be banks, taking huge profit from high risk proprietary trades with government-backed money, instead of one of a network of small conservative local institutions serving their domicile communities merely as intermediaries of money through local deposits for nominal fees.

Sheila C. Bair, chairman of the Federal Deposit Insurance Corp, described the TBTF problem as: “It fed the crisis, and it has gotten worse because of the crisis.”

The US financial system is looking more like a financial trust of a small number of super banks operating with deliberate moral hazard backed by ever ready government bailouts, while consumers are increasingly faced with fewer choices for financial services from competitive providers.”

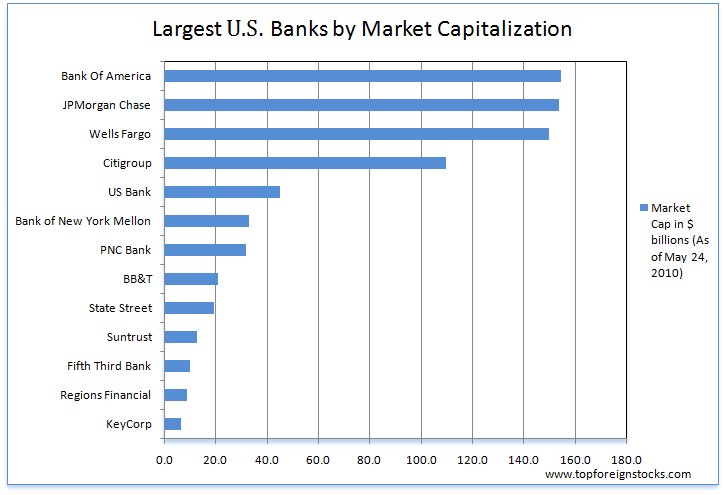
The chart below shows the 13 Largest 13 U.S. Banks by Market Capitalization:

Click to Enlarge

untitled.png

The largest four also hold the largest bank deposits. The market cap of US bank (USB) is less than half of Citigroup, the fourth largest bank. The market cap of Bank of America is higher than all the non superbanks except U.S. Bank.