A Look at the Petroleum Sector of Norway

The Petroleum Sector is the largest industry of Norway. Today there are 60 oil fields in production on the Norwegian Continental Shelf. In 2008, they produced 2.5 Million barrels of crude oil per day. Norway is one of the top oil producing countries in the western world. In 2008, Norway is projected to surpass Canada to become the second largest natural gas producer in the world.

The Norwegian government receives significant revenues in the form of tax revenues from the sector. In 2008, this sector accounted for 34% of the state’s total revenues.  The revenues are allocated to a special fund called the “Government Pension Fund – Global” which had a value of NOK 2275 Billion at the end of last year. (Note: 1 NOK = 0.1644 US$ on August 15,2009)

Growth of the Government Pension Fund – Global

Government Pension Fund – Global

Importance of the Petroleum Sector for Norway (click to enlarge)

Norway-Oil-Sector

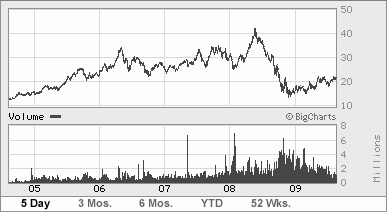
The largest oil and natural gas company in Norway is  StatOilHydro (STO) which was formed by the merger of Statoil and Norsk Hydro’s oil and gas operations  in 2007. StatOilHydro has presence in 24 countries and operates 2,300 service stations in Scandinavia, Poland, the Baltic States and Russia. Year-to-Date the stock is up nearly 31%.

5-Year Performance of StatOilHydro (STO):
STO-performance-5-year

Top Countries to which Norway exported its natural gas in 2008:
(click to enlarge)

Norway-Top-Natural-Gas-Exports

Source: Facts 2009, The Norwegian Petroleum
Ministry of Petroleum, Norway
Knowledge is Power: China Exporters, Australia Property Edition

Retirement (Special report): 10 stocks for the long term.They aren’t sexy. But for a retirement nest egg, they’re keepers.

Half of Europe’s festive products are made in or traded through the city of Yiwu, but business this year is at a record low.Chinese exporters hit by global recession

The UK is at risk of bankruptcy tourism as indebted people turn to Britain to take advantage of its leniencey, an insolvency expert claims.UK could face wave of bankruptcy tourism

Government Pension Fund-Global, Oslo, returned 12.7% on its investments in the quarter ended June 30 on the strength of its equity allocation. Equities help Norwegian fund return 12.7% for quarter

The Sage of Omaha has redefined the idea of value investing. But will its principles survive his inevitable passing? What Would Warren Do?

The inside story of how the government forced Bank of America to acquire the financial management giant and its spiraling losses. The Final Days of Merrill Lynch

Aussie property about to ride a big wave.AUSTRALIA’S property sector is about to catch a wave but homeowners and investors do not need to worry about a wipe-out.

Money-Market-Funds

Democratic Vs. Non-Democratic Countries – Why Does Economic Growth Differ?

Democratic countries have higher economic growth than non-democratic countries. The following chart shows the difference in GDP growth per capita between Singapore and Jordan:

Singapore-Jordan-Per-Capita-GDP-Growth

Source: Democracy, diversification, and growth reversals by David Cuberes , Michal Jerzmanowski

The above chart shows the exponential growth enjoyed by the citizens of Singapore over the past few decades compared to Jordan which has stagnant growth. This is because Singapore is  a democracy while Jordan is not. Jordan is a a constitutional monarchy with a representative government. executive authority lies with the King King Abdullah II and his council of ministers.

Some of the reasons for the difference in economic growth between Jordan and Singapore are:

  • Openness to trade
  • Protection of property rights
  • High investment rates,  etc.

Singapore has the above factors in abundance while Jordan lacks.

To read more , go here.

Can China Convert to a Consumer-Based Economy Successfully?

Investors worldwide are focusing on China as it has become the top-performer among the emerging markets year-to-date. Media reports have even mentioned China as the country that will pull the world out of the current global recession.

Until last year  China was mainly an export-driven economy. Overseas demand for all kinds of consumer goods kept the Chinese economy growing strong.However since the credit crisis and the recession adversely affected exports,China implemented a 4 trillion yuan ($706 billion) stimulus plan that concentrates heavily on infrastructure spending and raising consumption levels by individuals by offering subsidies for goods. However moving forward will China be able to depend less on exports and convert the economy to be a consumer-based economy?. Nobody knows the answer for sure.

China is heavily dependent on exports as the chart shows below. During 2001-08 60% of the GDP growth was related to net exports and investment in sectors related to trade primarily manufacturing. This was increase from 40% in the 90s. The estimated contribution of exports to GDP growth as about 30% for 2001-08 up from 15% in the 90s. The tremendous growth in exports lead China to account for 9  1/3% of world’s export in 2008.

China

China has one of the highest investment rate in the world at about 40% of GDP. The majority of the investments go into manufacturing, infrastructure and real estate. Manufacturing accounts for 30% of investment since exports of finished products require large investment in factories.

China-Investment-Rate

Source: IMF Working Paper, Is China’s Export-Oriented Growth Sustainable? by Kai Guo and Papa N’Diaye

It will take a long time for China to retool the economy to stimulate domestic demand.As consumers in the developed world drastically cut down consumption of cheap imported goods, China’s exports would suffer more. China’s exports have been decreasing on an year-over-year basis for the past nine month.Compared to last year, exports was down 23% in July 2009.

The Chinese leadership is well aware of the task ahead of them in converting the economy to be consumer-based as opposed to export-driven.

“The biggest problem with China’s economy is that the growth is unstable, unbalanced, uncoordinated, and unsustainable.”
Premier Wen Jiabao, National People’s Congress Press Conference, March 2007.

Which Banks Are More Risky – The Largest EU or US Banks ?

The largest of the European Union (EU) banks fell more than their US peers in the recent credit crisis since their leverage ratio and the exposure to market risk was higher.Many European bank stocks such as ING Bank (ING), Royal Bank of Scotland (RBS), Societe Generale (SCGLY), Commerzbank(CRZBY), Lloyds Bank(LYG) fell sharply last year and thru March. For many investors this was a big shock since they assumed that European banks were not involved heavily in the sub-prime mess.

If banks have high leverage ratios then their capacity to absorb losses becomes less.The leverage ratio for the financial sector in the Euro area increased to about 70% of the GDP between 1999 and 2007. But in the U.S. this ratio grew to only 40% during the same period.

The chart below shows the Leverage and Exposure to Market Risk of the Largest EU and US banks between 1998-2008: 

Click to Expand

EU-US-Banks-Leverage-Market-Risk

Source: Leverage: total liabilities/net tangible equity. Exposure to market risk: total securities/net tangible equity. Data on 2008 are estimates. Source: R&S – Mediobanca 2009 

Simple explanations for global financial instability and the cure: Keep it simple by Jacopo Carmassi,   Daniel Gros, Stefano Micossi

The large  EU banks had an average leverage ratio higher than US banks (top section of chart).The average ratio for EU banks was about 35 but it reached to 70 or even 80 for some German, British and Swiss banks.

Compared to the US, Europe has tougher regulations for the banking sector. Despite this, European banks  not only over-leveraged but also exposed themselves to some of the riskiest assets out there similar to the large banks in the US. This situation occurred because of the lax oversight by the regulators in European countries. Besides European banks also wanted to boost their profits to high levels even if meant taking huge unnecessary risks.