Two Foreign Utilities with more than 6% Dividend Yield

CPFL Energia S.A. (CPL) of Brazil and National Grid plc (NGG) of UK current have dividend yields of over 6%.

CPFL Energia S.A. (CPL earnings growth is about 35% and the revenue growth is about 10%. Last year the company had a total revenue of $5.8B. It is one of the highly profitable electric ) is an electric utility with 6.4 Million customers. The average annualutilities with a net margin of 12.60%. The current dividend yield is 7.40%.

Uk-based National Grid(NGG) operates both in the electricity and natural gas business. In the UK, it delivers gas to 11 million homes. The US division of National Grid delivers electricity to 5 million customers in Massachusetts, New Hampshire, New York and Rhode Island. Average annual earnings growth is flat in the last 5 years and the profit margin is about 6%. NGG pays a dividend of 6.87%. On October 15, S&P; put a Buy recommendation on National Grid’s ADS.

S&P; stated:
” We continue to believe that NGG’s low-risk regulated revenues and dividend policy make the ADSS attractive for above-average total return. We expect the board to implement an 8% increase in the dividend, which currently yields about 6.4%, and above the average yield of about 5.0% for U.S. peers. We still see EPS of $3.80 for FY 10 (March) and $3.95 for FY 11. Assuming a weighted average cost of capital of 4.9% and terminal growth rate of 2.0%, we keep our 12-month target price of $53, reflecting a premium to U.S.-peers P/E of 13.9X our FY 10 estimate.”

With a juicy dividend of over 6% and possibility of a further increase in dividends NGG may be an attractive foreign utility stock now.

Nine U.S. Bank Stocks to Invest In Now

Despite the astonishing run up from this year’s March lows, some investors are searching for reasons to invest in bank stocks. There are many reasons to avoid to them but there are also some who believe that some banks are worth looking into.In this post let me list 9 U.S. banks in two sets that seem attractive relative to hundreds of other banks.

But before getting into the list, we must remind ourselves that the easy money in bank stocks may already be gone. For example, in Is the bank stock rally over? Peter Lee of Euromoney said:

“It is possible that the cosy narrative of crisis giving way to healing and recovery in the global banking industry might not progress quite so smoothly. Credit costs are rising and the worst might still be in front of banks, not behind them.

In the six months following their lows in early March, US financial stocks rallied by 135% to early October while the overall stock market rose 51%. In Europe, financial stocks put on 121%, compared with 54% for the overall market, and in the UK they rose 139%, compared with 45% for the market as a whole.

Forward price-earnings ratios in the broad US and European stock markets are now above historical averages, and for financial stocks in particular even above their pre-crisis levels.

Banks aren’t yet saying that the peak of credit woes has passed or is even in sight. Investors, however, don’t seem to care. “

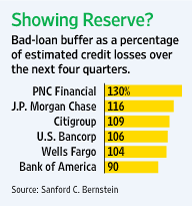
The first set of banks comes from the Journal’s article on November 2nd titled Investing in Banks? Check Loss Buffers.

According to this piece one metric that investors must consider when selecting bank stocks is the bad-loan reserve also called as provisions. “If a bank has a strong reserve against credit losses today, its earnings are likely to recover much more quickly than at less-girded peers.”

The six banks in this article listed are:

Us-Banks-Loss-Reserves

Source: The Wall Street Journal

According Bernstein’s research PNC Financial (PNC) has the highest bad-loan buffer at 130%. Citigroup’s(C) buffer of 109% is equal to the charge-off rate over the next 12 months. The bank with lowest buffer is Bank of America(BAC) at 90%.

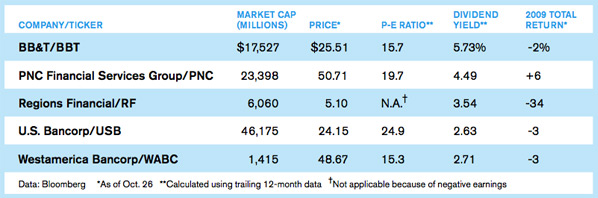
The following list of regional banks increased their branches last year during the global turmoil. BusinessWeek says that this may give them an advantage as the industry recovers. For example, last year PNC of Pittsburgh gobbled up National City of Cleveland gaining hundreds of branches in Ohio and other states.

US-Regional-Banks

Source: BusinessWeek

U.S. Bank (USB) continues to grow by acquisitions and is a strong performer among the regional banks. South-based BB&T (BBT) and Regions Financial (RF) also have strong franchises and offer high dividend yields now.

Nine Canadian Basic Materials Stocks

The S&P; ADR Index is up 30.18% YTD. As Canada is a resource-rich country, nine Canadian companies are part of the materials component of this index. The majority of these companies are gold miners.

The Nine Canadian Basic Materials sector stocks that trade in the NYSE are:

  1. Agnico Eagle Mines Ltd (AEM)
  2. Agrium Inc. (AGU)
  3. Barrick Gold Corp(ABX)
  4. Goldcorp Inc (GG)
  5. Kinross Gold Corp (IAG)
  6. IAMGOLD Corp (KGC)
  7. Potash Corp. (POT)
  8. Teck Resources Limited (TCK)
  9. Yamana Gold Inc. (AUY)

Potash and Agrium are large agricultural products producers with operations mainly in fertilizer manufacturing. Both of them had great runs in the past when food prices soared worldwide and the demand for commodities increased several fold from emerging market countries. Higher global demand for fertilizers and seeds in the future will benefit these companies. With the spot price of gold rising to a record $1,084.90 per oz yesterday some are predicting that it will go even higher.A journal article says that the next stop may be $1,100.

Could the U.S. Banking Crisis Follow Japan’s?

Nine more banks failed in the U.S. last Friday bringing the total to 115 this year. Still many more are at risk of failure thru the end of this year and next year. Despite the talk of recovery banks are not out of the woods yet. Though the financials in the S&P 500 are up about 12% so far this year, bank stocks have long ways to go before they return to the normal that existed pre-2008.

So what holds for the U.S. banking industry in the future? Will the U.S. banking industry go thru similar phases that the Japanese banks went thru in the past?

The following chart shows the various phases in Japan’s Banking crisis:

Japan-Bank-Crisis-Phases

Source: Regional Economic Outlook: Asia and Pacific, IMF

In the first phase from 1990 thru 1996, the banking crisis unraveled in Japan and was followed a fragile recovery followed by the withdrawl of fiscal stimulus. If this were to occur in the U.S., we are now only in the second year of the phase one. Another 6 more years may have to go before phase one ends. In the next phase, renewed stress followed due to monetary tightening. Japan also attempted a second recovery in this period. So from 1990 to 2000, Japan had its lost decade during which recovery was attempted twice. Finally after the dot com crash, private demand picked up and many Japanese banks and companies were restructured which led to a sustained recovery from 2001 thru 2007. Since Japan exports heavily to the largest emerging market of China, the trade helped Japanese economy gain a solid footing after a decade of flat to sluggish growth. It is too early to tell how the US banking industry will look like in the next few years.

As more and more small community banks disappear, regional banks such as U.S. Bank (USB), Regions Financial (RF), PNC Bank (PNC), etc. will become larger by acquiring the assets of failed banks on the cheap.