Multinational Companies with Large Exposure to Emerging Markets

Companies from developed countries are increasingly investing heavily in emerging markets to participate in the tremendous growth. The BRIC countries (Brazil, Russia, India and China) are the preferred destination for these companies.

Foreign Direct Investment (FDI) fell sharply last year to $1 Trillion from $1.7 Trillion in 2008(Source: UNCTAD). However the overall trend of FDI flow is still up in the last decade since FDI into many of the emerging countries peaked in 2008.

OECD Economist Javier Santiso mentioned in The rise of “euro-emerging” multinationals:

“China drew a comfortable $90 billion from foreign companies investing in the country’s factories and other productive assets in 2009. In December 2009 alone, China attracted more than $12 billion in FDI, up 103% from a year earlier. Some emerging countries like Peru even enjoyed a rise of 28%. Most of the emerging countries however saw a reduction of FDI – but from a peak in 2008. In Brazil, for example, FDI fell by half in 2009 but from a historical record in 2008 of $45 billion. In Colombia, the fall has been less pronounced (-15% in 2009) but also from a peak in 2008. In India, according to the national estimates, FDI in the year to March 2010 would be about $18 billion, from a peak of $27 billion in the year 2008/2009.”

Some investors prefer to invest directly in emerging market companies. However this comes with high risk. For example, during the credit crisis in 2008 the markets in BRIC fell more than those in developed countries. Except Brazil, the other three countries fell more than 50%. Compared to this, markets in the UK, Canada, USA, Germany, etc. were all down less than 50%. In 2009, when the global markets rebounded the BRIC countries rose sharply then the developed markets. Despite this performance, some investors prefer to invest in emerging markets via developed market companies that have high exposure to those markets. This is a simple but effective strategy to profit from the growth of developing countries.

The number of people in the middle class category in BRIC countries is growing. An estimated two billion people could join the global middle class by 203o, mainly from India and China according to a Goldman Sachs report. In addition to the rising middle class and growing incomes, infrastructure demand is also expected to rise over the next decade. Hence companies that are well positioned to cater to the needs of the emerging markets will profit nicely.

Which companies from the Developed Countries have high exposure to BRICs?

Goldman Sachs has identified 50 companies (‘BRICs Nifty 50’) that have excellent potential to benefit from growth in the BRIC countries.

The BRIC ‘Nifty 50’ Developed Market companies are listed in the table below:

[TABLE=400]

Source: Global Portfolio Strategy, The BRICs Nifty 50: The EM & DM winners
Goldman Sachs

Investors may also want to check out some of the multinationals mentioned in Javier Santiso’s article. The ‘Euro-emerging’ companies with large exposure to emerging markets are:

  • Renault, Schneider Electric, Lafarge(LR) and Rhodia (RHA) of France
  • MAN, Volkswagen (OTC: VLKAY) of Germany
  • Philips (PHG) of The Netherlands
  • Arcelor Mittal(MT) of Luxembourg
  • Tullow Oil (OTC: TUWOY), Kazakhmys, Cairn Energy of the UK
  • Telenor of Norway
  • Banco Santander(STD), Inditex, Iberdrola (OTC: IBDRY), Endesa (ELE), Gas Natural, Telefonica(TEF) of Spain
Ten Highest Dividend Paying Stocks from the Eurozone Countries

The Dow Jones EURO STOXX Select Dividend 30 Index consists of the 30 high-dividend-yielding companies of the Eurozone. The Eurozone countries include Austria, Belgium, Finland, France, Germany, Greece, Ireland, Italy, Luxembourg, the Netherlands, Portugal and Spain.

The ETFlab DJ EURO STOXX® Select Dividend 30 ETF tracks the performance of the above index.  The Top 10 holdings in this ETF are:

1. Banco Santander (STD)
Current Dividend Yield: 5.36%
Spain

2.Vallourec
France

3. Erste Group Bank (OTC: EBKDY)
Current Dividend Yield: 2.27%
Austria

4. Metso Oyj (OTC: MXCYY)
Current Dividend Yield: 3.04%
Finland

5. Wartsila OYJ
Finland

6.Banco Popular Espanol
Spain

7. Unilever NV (UN)
Current Dividend Yield: 1.77%
The Netherlands

8. Bilfinger Berger AG
Germany

9. Enel Spa (E)
Current Dividend Yield: 6.08%
Italy

10. Wereldhave nV
The Netherlands

Please note that the dividend yields are noted only for the companies that trade as ADRs in the US markets.

30 S&P 5-STARS Rated Stocks

The S&P’s Platinum Portfolio consists of the top rated stocks from the Standard & Poor’s Fair Value Portfolio and its Stock Appreciation Ranking System (STARS). To be eligible in this portfolio, all stocks must carry a 5-STARS rating and a Fair Value Ranking of 5.

The table below lists the 5-STARS rated stocks in the portfolio as of February 19th:

[TABLE=399]

New York Community Bancorp (NYB) currently has a dividend yield of 6.40%. With the purchase of AmTrust Bank of Cleveland, Ohio the bank is expanding from its traditional footprint to Ohio, Arizona and Florida. The food products company General Mills (GIS)  and the world’s largest retailer Wal-Mart (WMT) are also in this list.

Stocks Outperform Bonds in the Long Run

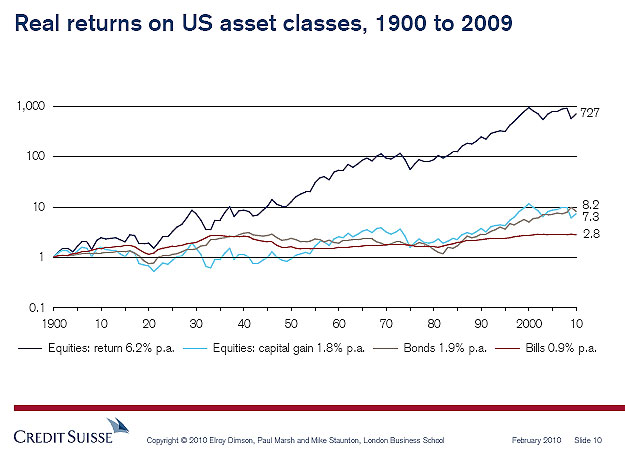
The 2010 edition of the Credit Suisse Global Investment Returns Year Book confirms that equities outperform bonds over the long term. The chart below shows the performance of U.S. stocks, bonds and T-bills from 1900 thru 2009:


US-Market-Returns-1900-2009


A $1,000 invested in U.S. equities in 1900 would be worth $727,000 now. This number is adjusted for inflation. The real rate of return equals to 6.2% which is very good. However it must be noted that the majority of the returns came from dividend reinvestment and not capital appreciation. Capital gains accounted for just 1.8% per year.This study proves again the importance of investing in dividend paying stocks and dividend reinvestment. When compared to stocks, the rate of return on bonds and T-bills is very low.

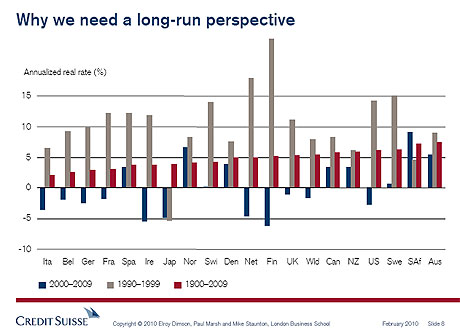
The following graphic shows the rate of return for equities over different time periods:


Stock-Returns-Comparison

Source:  Credit Suisse Global Investment Returns Year Book 2010

14 Cheap International Closed-End Funds

The Wall Street Journal’s Jason Zweig has written an interesting article on the risks of high yields paid by closed-end funds. Closed-end funds trade like stocks and are considered cheap when they trade at a discount to their NAVs. They trade at a premium if the market price is more than their NAV. Closed-end funds can be extremely volatile especially during tough market conditions.

Jason Zweig mentions three funds which recently traded at a high premium and whose high yields may be unsustainable. The three funds noted are:

Pimco Global StocksPLUS & Income Fund (PGP)
Pimco High Income Fund(PHK)
Gabelli Utility Trust (GUT)

Investing in closed-end funds just for high yields is risky. However they can be considered for gaining some diversification in a portfolio.

The following 14 International Closed-End Equity Funds trade at a discount of at least 10% to their NAVs:

1. The Central Europe & Russia Fund (CEE)
Current Premium/Discount: -11.83%

2. Morgan Stanley Eastern Europe Fund (RNE)
Current Premium/Discount: -10.04%

3. The Mexico Fund (MXF)
Current Premium/Discount: -12.23%

4. First Israel Fund (ISL)
Current Premium/Discount: -10.05%

5. Korea Equity Fund (KEF)
Current Premium/Discount: -10.90%

6. First Trust/Aberdeen Emerging Opportunity (FEO)
Current Premium/Discount: -11.44%

7. Clough Global Equity (GLQ)
Current Premium/Discount: -13.88%

8. Clough Global Opportunities (GLO)
Current Premium/Discount: – 13.07%

9. The Thai Fund (TTF)
Current Premium/Discount: -15.55%

10. The Malaysia Fund (MAY)
Current Premium/Discount: -14.08%

11. The Taiwan Fund (TWN)
Current Premium/Discount: -11.53%

12. The Thai Capital Fund (TF)
Current Premium/Discount: -17.01%

13. Morgan Stanley Frontier Emerging Market Fund (FFD)
Current Premium/Discount: -13.91%

14. Emerging Markets Telecommunications Fund (ETF)
Current Premium/Discount: -12.30%

Source: CEFA