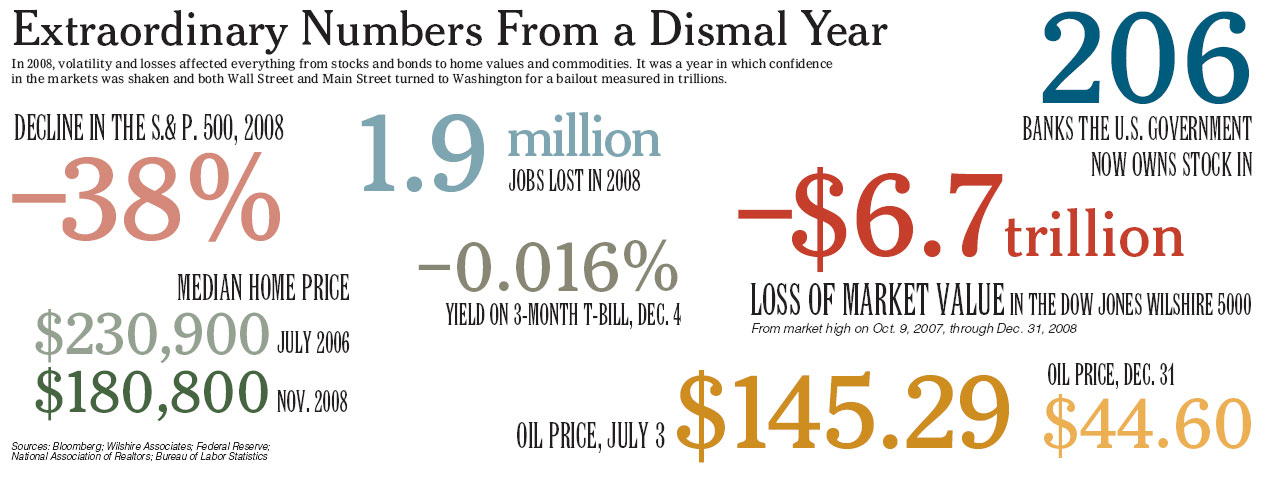SocGen Raises Dividend

Societe Generale SA, one of the largest banks in France raised the dividend today by 33% to 1.2 Euros a share. SoGen trades in the US in the OTC market with ticker SCGLY.

Some of the key points in the 4th Quarter,2008 earnings report:

  • French consumer lending helped the bank offset losses in international operations
  • Net Income was 87 million Euros
  • SocGen said 2009 will “probably remain challenging”
  • At the end of 2008, the Tier 1 capital ratio stood at 8.8%

Last year the bank suffered heavy losses due to a rogue trader named Jerome Kerviel. Since the bank owns Komercni Banka AS in the Czech Republic the bank may report more losses this year due to severe economic issues in Eastern European countries. SocGen also owns Rosbank and BRD-Groupe Societe Generale, Romania’s second- biggest bank.

Source: Bloomberg

SocGen Reports Fourth-Quarter Profit on French Retail (Update2)

More from SocGen’s IR site:

Fourth Qtr and 2008 Full year Results Report

Detailed Financial Data Presentation

Disclosure: Long SCGLY.

Composition of Loan Portfolios of FDIC-Insured Institutions

Have you ever wondered how much of the total outstanding loans in the USA is related to residential mortgages? Residential mortgage loans have been attributed as the main culprit behind the credit crisis. To be more precise, it is the sub-prime residential mortgages.

Some say that other type of loans such as credit cards, commercial construction loans, etc. will be the next to collapse. To get a clear picture, I found the following chart from the FDIC’s Quarterly banking Profile for 3Q, 2008:
(Click to enlarge)

Residential mortgages constitute the largest portion of all loans.Construction and non-farm non-residential real estate loans add up another 21%.Hence overall real estate related loans form the most of all loans. Unless the toxic loans in this real estate assets are cleaned up the housing sector will continue to spiral down more.

What Is The Future Of US Community Banks?

Created in 1933 to restore confidence in the nation’s banking system, the The Federal Deposit Insurance Corporation (FDIC) insures deposits at 8,384 banks and savings associations in this country (Source: FDIC News Release – 2/5/2009). A vast majority of these FDIC-insured banks are small and medium community banks. In this article lets review the community banking system and analyze what the future holds for them.As per the Independent Community Bankers of America (ICBA), community banks constitute 98% of all banks in the US. Some of them are small and some of them are medium sized with assets ranging from $10M to a few billion. Community banks are an important source of lending for small businesses. “According to the SBA Office of Advocacy, community banks provide 35% of the total dollar amount of loans to small businesses under $1 million dollars, despite comprising just 12% of industry assets.”

Considering the above facts it would seem that the small and medium banks must be helped during times of crisis. However that is not happening. Following “the too big to fail” theory, the Feds have been helping large banks survive with massive cash infusions while shutting down weak community banks. In 2008, of the 25 banks failed banks just two of them large institutions. They were Washington Mutual and IndyMac Bank accounting for 91 percent of the assets of all the failed banks in 2008.

This year so far the following 13 banks have failed:

Pinnacle Bank of Oregon, Beaverton, OR
Corn Belt Bank and Trust Company, Pittsfield, IL
Riverside Bank of the Gulf Coast, Cape Coral, FL
Sherman County Bank, Loup City, NE
County Bank, Merced, CA
Alliance Bank, Culver City, CA
FirstBank Financial Services, McDonough, GA
Ocala National Bank, Ocala, FL
Suburban Federal Savings Bank, Crofton, MD
MagnetBank, Salt Lake City, UT
1st Centennial Bank, Redlands, CA
Bank of Clark County, Vancouver, WA
National Bank of Commerce, Berkeley, IL

Of the over 700 community banks listed in the markets, the small ones are strong due to lower exposure to the subprime mess. A recent Banker article says that the medium-sized banks face the greatest threat. Most of the banks that failed in 2008 and in 2009 are community banks.

Medium-sized banks are face tough challenges ahead. Camden Fine, president of the Independent Community Bankers of America (ICBA), which represents the country’s almost 8000 community banks says “They are between community banks [which have assets of $1bn or less] that can fend for themselves, and the biggest banks that are considered too big to fail.”

While the large mega banks are asking and getting Uncle Sam’s help to continue operations, some small and medium sized banks are actually rejecting federal capital infusions. Small banks such as the 20-branch Burke and Herbert Bank in Virginia continue to attract more deposits. Last year during the Wachovia takeover saga, Edmund Burke of the bank commented “we had an influx of new deposits of $66m over a four-week period. That’s a year’s growth in deposits for us normally”.

Instead of just propping up the mega banks such as Citibank (C), Bank of America(BAC) and the like with tax payers’ dollars it may be time that the government supported the strong community banks. However the weak community banks must be closed down though. With more than 10 months to go, we can expect to see some more community banks fail this year.

Will US Pension Funds Suffer More Losses in 2009?

This week the Organisation for Economic Co-Operation and Development (OECD) released the OECD Private Pensions Outlook 2008 report. This report analyzes the private pension systems in various countries and compares their performance in terms of fees, risk allocation, etc.

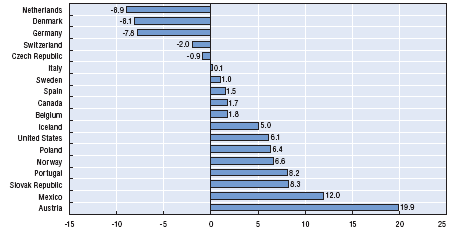
One of my key observations in this report is that the pension funds in the USA increased their equity allocations between 2001 and 2007 to over 60% of the total assets they managed. Since the markets fell heavily 2008, they were exposed to large losses. Other developed country pension funds that increased equity allocations were Ireland, Norway, Portugal, etc.

Chart – Differences in Equity Allocations between 2001 and 2007 in select OECD countries:

OECD pension

Source: OECD

As we can see from the above chart, Germany, Denmark, The Netherlands and Switzerland reduced their equity allocations in the same period. The report says: “In the case of Denmark and the Netherlands this portfolio reallocation appears to be partly driven by the introduction of stricter, risk-based funding requirements.”

Last year by October end, total losses in private pension plans in developed countries were USD 5 Trillion. Out of that USD 3.3 Trillion were in the US alone (Source: OECD). In 2008, about $7 Trillion shareholder wealth was lost in the US as per the New York Times.

Year 2008 in Numbers Graph from The New York Times:

2008 in nUmbers

(Click to enlarge)

US investors have to monitor their pension funds’ performance more closely this year as they have raised their equity allocations in 2008.

The S&P is down 8.46% year-to-date and the financials are down an incredible 30.10%. Ans we still have ten and half months to go. Faced with huge losses some investors have cut down their investments in the equity markets. Companies such as FedEx,Eastman Kodak, Motorola, General Motors and Resorts International have also cut their 401K matching contributions to save cash. Hence if the economy does not respond to the stimulus plans of the Obama administration then it is highly likely that US pension funds will have negative returns this year on top of losses incurred last year.

Country Specific Closed-End Funds

Many of the closed-end funds are trading at a discount to NAVs. When these funds trade at a discount they are considered to be cheap. Closed-end funds can be swing wildly during volatile markets such as the one investors are enduring.

The following are five cheap closed-end funds:

1.New Germany Fund (GF)
Discount to NAV: (21.57%)

2. Spain Fund (SNF)
Discount to NAV: (14.62%)

3.Malaysia Fund (MAY)
Discount to NAV: (11.45%)

4.Mexico Fund (MXF)
Discount to NAV: (9.43%)

5.Korea Fund (KF)
Discount to NAV: (5.73%)